elements Of Finance.netÓ
Shareable Resources for Teaching
& Learning
in the Arts & Sciences, Technology, Engineering, Mathematics,
Financial Economics
& Jurisprudence (aSTEMfej )
Writings by prof-td@elementsOfFinance.net
The elements Of Finance book: http://elementsoffinance.net/elements.pdf (pre-completion v2020.0818)
Most recent preview of in-progress Chapter
1.4: http://elementsoffinance.net/palette.pdf
Back history of the preview: http://elementsoffinance.net/support/palette-20261011.pdf
http://elementsoffinance.net/support/palette-20251210.pdf
http://elementsoffinance.net/support/palette-20250213.pdf
http://elementsoffinance.net/support/palette-20230220.pdf
About the baby-boomer
author…
Parents and society taught me the value and
excitement of learning. During 2 years in John Adams Junior High School in historic
downtown Charleston WV, the thrill of diagramming sentences into parts during
English classes coupled with tripartite checks and balances during Civics
classes adding onto beautiful angles of motion during Math classes, that all
put me in the comfort zone for liking learning. Reinforcement came during 2
years of study at nearly new George Washington High School in the suburban
hills south of downtown Charleston with Biology classes teaching about DNA and textbook
imagery of mitochondria and bacteria through an electron microscope, seminar
classes discussed thoughtful world literature, and a Business Typing class
ignited the cortical columns of my relatively new teen-age brain as never has
happened before or since. These secondary school events set a concrete
conviction in motion for me to obtain after graduation as a George Washington
Patriot in June 1970 a
college degree in Biology (not pre-medicine) and eventually a doctorate, should
circumstances permit.
None before me in family lineage had
gone to college though truthfully very little family history was told to me and
even less was written. Similar to astronauts, Presidents and great
grandparents, the only time I had ever seen them or a Professor
was on TV! El Camino Community College
during primary school years in California and Morris Harvey College in
Charleston were the only colleges that I recall seeing prior to HS graduation. My
Father during World War 2 was Chemistry Club President at Trona HS and his
enthusiasm when soldering transistors and diodes onto a circuit board in 1962
while making a Heathkit Hi-Fi Stereo Receiver or
interpreting oscilloscope waves for targets on which I’m clueless, that
behavior inspires questioning and learning. A dozen years after my HS
graduation, right on time, in August 1982 the successful final defense
of my doctoral dissertation at the land grant institution Purdue University in West
Lafayette Indiana certifies me to “Pile*it*Hip*Deep.
The preceding spring Boston College
Department Head Dr. Jerry Viscione thankfully extended an invitation for me to
join the ranks of about 10 faculty in the Finance Department in Chestnut Hill
Massachusetts, a stop on the Green Line trolley passing Fenway Park toward
downtown, commencing September
1982. My preconception was that Boston was the metropolis for higher
education in the USA. With gratitude for the goodness that domicile for 4 years
in Tippecanoe County IN delivered to me and to my spouse, a sharp New Yorker
pointed and direct that has illumined my pathway since September 1971
during our freshman year at La Universidád Católica
de Puerto Rico when sunshine silhouetted her tardy entry into World Lit, we
loaded household property into a 26’ rental box truck and our 2 preschoolers
(Boilermakers before Hoosiers) into our 1978 Honda Accord. In August 1982 we headed to Boston thankful
to buy our chosen house with a 30-year fixed rate bank mortgage at an annual
percentage rate (APR) of 17.25%. We were thankful for that chance and hopeful
that our starter home in Indiana at 9.25% would sell before the 6-month
seller-financed note came due!
My 7-years in service toward the many
interests of life with family, career, and Boston College were incredible,
simply unbelievable years with a sequence of highly improbable events that continue
to influence me. Afterall, the student athlete gridiron receiver that caught
student athlete Doug Flutie’s winning pass with 0.0 seconds on the clock
against Miami was in my undergraduate Investments class the preceding semester!
Finding how to make something out of zero is certainly resourceful. Finding
zero forms the foundation for numeracy. Discussion below in item #1 begins this
side of midway through my BC years with an article about the linkage between tax
policy and the intrinsic value of stock prices.
1. This study, “Tax Policy and
Stock Prices” is co-authored with Dr Patric H. Hendershott, Head of
my dissertation Committee at Purdue University (1978-82; Full Committee: Profs
Gary Schlarbaum, James C. Moore, and Sheng Cheng Hu). This study introduces the
specification from my dissertation for intrinsic value in order to measure the valuation
effects from tax law changes on the real nonfinancial corporate fixed capital
stocks in the USA. Sheer gratitude flows
from me to Prof Hendershott for directing this study through the National
Bureau of Economic Research (NBER).
http://elementsoffinance.net/support/ntj_tax_policy.pdf
I presented a version of the study [1986a Presentation
to the NBER ]
four decades ago at the NBER Summer Institute Research Series. Distinguished
Profs seated around the conference room table besides Prof Patric Hendershott
(Ohio State U & NBER Research Associate) included moderator David Bradford
(Princeton U), Martin Feldstein (Harvard U, President and CEO of the NBER),
Mervyn King (London School of Economics), Jonathan Leape (also LSE), Alan
Auerbach (HarvardU), and a few others. Each held a
study similar to the NBER working paper [1986b NBER
WP #2094 ] that
went public about 2 months later. Room discussion by Prof Leape
clarified that the risk premia for tax shields differs from non-tax shields
even though, as is also true and I clarified, the equity financing rate
capitalizes the cash flows to equity at the cost of capital residual rate.
Prof Feldstein saw the gap between intrinsic value and current replacement cost
as problematic. After finishing amidst salutations, Prof Feldstein asked for me
to meet in a few days with capital stock specialist Charles Hulten (U Maryland)
for discussion. After exiting alone from the conference room to the hallway the
next presenters Lawrence Summers (Harvard U) and David Cutler (MIT) were going
in. That gave me opportunity to offer Prof Summers thanks for the fantastic
discussions on economic income in Feldstein and Summers [1979a] that
were pivotal for me developing a dissertation proposal at Purdue. The encounter
also gave opportunity for me to confess some confusion following his
Q-trajectories [1981a] to their point!
Two months after the presentation my home
phone rang about 8:30am. Though answering the phone with a poopy baby diaper
in-hand before heading to my Boston College office, I hear “Hello, this is
Fischer Black,” then Managing Director at Saloman Brothers and forevermore the MIT
prof that laid a firm foundation for standardized derivative security markets.
The 45-minute phone conversation about intrinsic value remains a cherished
& inspirational event in my half century with universities of higher
learning. “Tax Policy and Stock Prices” was published in 1987 by editor Daniel
Holland (Massachusetts Institute of Technology) in the National Tax Journal.
The publication uses the label “fundamental value” for the same “intrinsic
value” object that my current writing uses.
My perspective of intrinsic value clarified
recently for me recalling a 2002 conversation with my then high schooler child
when she exclaimed “That’s wrong.” I previously said that “the earth goes in a
circle around the sun.” My teenager then explained more or less that the same
face of the moon watches the earth do its daily spin as if locked in heavenly
embrace while the two revolve around the sun. Gravitational forces flow from
each partner to the other such that their weighted average center of masses exists
as a spatial object, a location, that is much closer to the earth than the
moon. That special point is on the straight line drawn between the spherical
centers (almost) of the earth & moon. It is this spatial point in space on
that line of centers that behaves as a tiny containment, an invisible object,
that carries the mass of the two spheres in a revolution tracing a circle (more
elliptical) around the sun! The containments called the earth, moon and sun are
real. The containment carrying the mass of the embraced bodies is an imaginary
concoction of cognitive numeracy that humans discovered for explaining
observations of all kinds. That same numeracy explains that intrinsic value
corresponds to a point in the money dimension relative to which prices properly
position.
2.
This 1991 study explains that the three standard financial accounting valuation
methods for fixed asset stocks extend like telescopic vision through different information
sets. The historical replacement cost method measures historical investment
flows net of accumulated depreciation. The current replacement cost method
extends the measurements to account for incremental information on cumulative
class specific price inflation. The intrinsic value method in this article
accounts for general inflation, taxes, capital accumulation histories, and
depreciation schedules for real productive capacity.
http://elementsoffinance.net/support/jar_fundamental_value.pdf
Thanks
to co-author Prof Keith Shriver (Arizona State University) for questioning how
intrinsic value computations might compare to his dataset of actual used fixed
corporate asset prices. On May 8, 1991, I presented our findings in the
“Accounting and Taxation” conference at the University of Chicago Graduate
School of Business [ JARconference.pdf ].
Actual used corporate fixed asset prices track intrinsic valuations better than
historical cost or current cost valuations. A happy learning moment for me
occurred when discussant prof Ralph Sansing (Yale) having said that the
intrinsic valuation method “lacks a decision making
context” received a reply from Editor Katherine Schipper (UChicago) that the method
is immune to this criticism because the intrinsic value specification “has a
dimension of timelessness.” That dimension of timelessness forms the concrete
bond between the number and the real underlier that financial accounting
requires!
Easily envision a concrete bond by clasping
your two hands with forefingers outstretched side by side pointing skyward.
Unclasp hands keeping forefingers outstretched and lower one arm behind your back.
Point a second finger towards the sky. In the presence of a concrete bond then
behind your back the second finger also must extend. It’s not a choice. The one
is a reflection of the other at rest and in motion.
For finance the rates of return for a
hypothetical instantaneous zero-sum merger of two independent balance sheets
into one calibrate with zero. Suppose that a $100 wealth transfer, a gain, adds
onto a pre-merger equity base of $200 for the smaller of the merging companies thus
providing this shareholder class a 50% rate of return. Suppose that for the
other much larger merging company the pre-merger equity base is $9,800 (50%=
$100/$200). The $100 wealth transfer, a loss equal in magnitude to the other’s
gain, thus provides this shareholder class with a rate of return equal to –1.02040816% (–1.0204%=
$100/$9,800). The Elements of Finance
book [2016] explains that
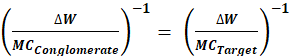 +
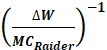
Each
right-hand-side term is absolute value of the reciprocal of the percentage
change in market cap. The conglomerate equity base equals the sum of the two merging balance sheet equity accounts, $200 + $9,800 equals $10,000. Because 50% is identical to ½
then then 2 is its reciprocal. 98 is identical to $100/$9,800. The two right hand side terms sum to
100. The left hand
side reciprocated equals
$10,000/$100, that is 100. The zero sum
merger is a well-defined example of the isoperimetric union that gaplessly links all dimensional sizes.
3. This 1988 study tests whether actual stock
returns for an industry in response to tax policy changes map to changes in
intrinsic value.
http://elementsoffinance.net/support/aer_stock_prices.pdf
A
fundamental finding is that the responsiveness of balance sheet intrinsic value
to a change in the financial cost of capital may be positive or negative and depends
on a ratio of percentage changes, that is an interest elasticity (“duration”)
of the return streams for marginal investments relative to that for total
assets. When the ratio of elasticities exceeds unity, a plausible scenario in
some scenarios, then intrinsic value rises with a rising cost of capital and
falls with a falling cost of capital. An increase in the cost of capital is
commonly thought to unidirectionally depress intrinsic value – wrong! Thanks to
Boston College co-author colleague Hassan Tehranian that while comparing the
excess stock return numbers from his FORTRAN program with my predicted changes
of intrinsic value for 3 industries selected a priori stated “but how did you
know” – priceless. Besides lucky stats, I am even more grateful to HT for the
introduction outside my BC office door to Professor Billy Helms visiting
momentarily from the University of Alabama who, unbeknownst at the time, would
very soon offer guidance and growth opportunities for my family and me in sweet
home Alabama at the Department of Economics, Finance, & Legal Studies in
Tuscaloosa, the Queen City of LA (Lower Appalachia) on the Black Warrior River.
4. This 1991 study models and measures industry
level intrinsic values, an approach that focuses on the asset side of the
balance sheet. The ratio of industry
market capitalization to intrinsic value, labeled the overvalue ratio in the
study but more accurately labeled an overprice ratio, leverages rates of return
independently of required risk premia for liability side commitments. Namely,
for a $1 change in intrinsic value the resultant shareholder rate of return is
smaller for an overpriced industry (or company) and bigger for an underpriced
company irrespective of risk factors or preferences. It’s mechanical.
http://elementsoffinance.net/support/jpm_asset_valuation.pdf
This invited presentation [ JPMpresentation1991.pdf ] of an article from the
Journal of Portfolio Management (Editor Frank Fabozzi) at the Institutional
Investor Institute Quantitative Research Roundtable, an annual gathering of
securities market specialists October 17, 1991. During the 75
minute opening session at 8:30am Dr. Martin Leibowitz, then at TIAA-CREF,
presented “Asset allocation under shortfall constraints.” Seated beside him for
lunch, I was grateful for the opportunity to praise his book Investing (1992) for its enduring
lessons, especially the “riding the yield curve” and the “barbell” investment
strategies, that I used in class and for analysis. Prof Ken French (Dartmouth)
presented the Fama-French (1991) seminal work on Book-to-Market ratios and
multi-factor risk models. I briefly conjectured to Prof French that the explanatory
power of the Book-to-Market ratio (=Stockholders’ equity divided by market cap)
likely has little to do with being a risk factor and more with being
mechanically connected by concrete numeracy to the Overprice ratio (=market cap
divided by intrinsic value). Eventual findings by me in 2001 and 2002 in items
#8 and #9 support the conjecture.
5. This 1993 study reports that market
capitalizations for public utility industries track measurements of underlying
intrinsic values. Current replacement
cost measurements (CC) contain specifiable biases of economic value that depend
on capital accumulation histories, capacity depreciation schedules, tax
depreciation schedules, and cost of capital components. The intrinsic value model provides estimates
that contain incremental information beyond that inherent with the CC
measurements.
http://elementsoffinance.net/support/ntj_utility_valuation.pdf
This
1993 study was awarded the $5,000 prize sponsored by the National Tax
Association and the Public Utility and Railroad Workshop at Wichita State
University for the Distinguished Award in Applied Research.
6. The 1992 study below extends the sample from
item #3 in this list, the AER paper on stock prices and tax policy changes, to
10 industries (2-digit SIC code) rather than the 3 industries (2-digit SIC
code) as in the former study. The time required for collecting the information on
price to book ratios for debt securities compelled settling on 3 heavily
capitalized industries for the AER study. No other industries were examined as
we lacked key data. The additional evidence for all 10 industries shows quite a
bit of noise in the conclusions.
http://elementsoffinance.net/support/tfr_tax_reform.pdf
7.
For a conference on taxation at the American Institute for Economic Research (AIER)
at a manor for overnight attendees in Great Barrington Massachusetts that
included William Vickrey (Columbia U, Nobel Laureate in 1996) as well as public
finance specialists Richard and Peggy Musgrave, seemingly like magic an
invitation somehow flew my way from Prof Mason Gaffney (U California Riverside)
to the asset price approach to capital accumulation.
American
Institute for Economic Research-Conference
The
study documents a significant decline in the ratio of the pricing of fixed
productive assets relative to intrinsic values. Interestingly, at a subsequent
National Tax Association annual meeting Prof. Vickrey presented arguments that
the federal government was strangling the real exchange economy through unsound
public policy that inhibited capital formation.
8.
This 2001 study supports the 1991 conjecture in item #4 above that the price to
intrinsic value ratio mechanically inflates or deflates shareholder rates of
return. That is, the price to book ratio is not a risk factor but rather a
mechanical lever. Also, the study finds that penny stocks and extreme outcomes
provide evidence for the share market lottery premium.
http://elementsoffinance.net/support/jpm_lottery.pdf
This
article with then Ph.D. Finance student coauthor Quan Wen at the University of Alabama
shows that 1-in-4 of extreme positive stock returns occur for stocks priced
under $7 a share whereas 1-in-20 occur for medium and higher priced stocks.
Expectations are that rates of returns distribute independently of any specific
share price level. Those investors seeking extreme returns behaviorally respond
to a low stock price by perceiving a chance to own the winning ticket, however
remote, and willingly accept lower than average outcomes. The lottery premium
is larger in up markets than down markets and has become more costly as decades
roll on.
9. In this study, inspired and coauthored with
the then Head of the UA School of Accountancy, Prof Robert Ingram, we replicate
the Fama-French research relating the cross-section of stock returns to firm
size, beta, and total risk. Fama-French find that size relates positively with
average returns, and beta doesn’t, a result we replicate. Extending the
analysis, however, finds that as the extreme 2% of stock returns are censored
with trimmed least squares that the explanatory power of firm size persists
only in flat to falling markets. Systematic risk relates positively in
up-markets and negatively in down-markets, an outcome consistent with the
Sharpe-Lintner-Black capital asset pricing model for the single index beta
specification. We also find that average returns relate negatively with total
risk. The reduction in average return associating with an increase in total
risk reflects the tradeoff that investors behaviorally sacrifice for a chance
at an extreme albeit unlikely return.
http://elementsoffinance.net/support/jfr_risk_return.pdf
The
43 associate editors at Journal of Financial Research selected this
article as the Best of the Year and kindly sent us two a $5,000 prize to share.
10. Nearly all studies on fixed asset capital stocks
employ a user cost derived under assumptions inconsistent with the assumptions
used to derive their capital stock estimates. This study examines the
significance of this inconsistency and, more importantly, presents the
intrinsic value model that eliminates it. “Using the User
Cost” appears in
the Journal of Economics and Business [1986c]. The
study presents the model with continuous time math (calculus). Most my other writings
are, like all moments of time, discrete period math.
http://elementsoffinance.net/support/jecb_user_cost.pdf
The user cost accounts for phenomena besides the
financial cost of money such as physical depreciation in productive capacity
and the effects of inflation and taxation. The user cost of capital is akin to
the gross profit margin ratio of financial accounting with a numerator of EBITDA
(earnings before interest, taxes, and depreciation or amortization
charges). Synonyms for “user cost of
capital” include the rental price, shadow price, or time cost of capital. This
study refers to the product of the user cost times the quantity of real capital
as “the NOIs” (net operating income, a synonym for EBITDA).
John Keynes
writes in The
General Theory of Employment, Interest, and Money [1936a] that “the user cost constitutes
a link between the present and future.” Finance is all about time as often it’s
heard that time is money for the many that put their mind on their money and
their money on their mind!
11. This study is one of just a handful in the
literature that model the economic value of nonfinancial corporate assets to
establish that the well-known Tobin’s Q-ratio (= market cap to current
replacement cost) may systematically and routinely deviate from unity due to differences
in the timing of expected after-tax cash flows.
Still, empirical evidence shows little incremental explanatory power
from using tax-adjusted Q-ratios instead of standard unadjusted Q-ratios.
http://elementsoffinance.net/support/jpub_tax_bias.pdf
Nominal
Contracting and Contract Revaluations, Downs, T.W. and Hevert, Kathy 1998
12. Learn that the ex ante rate of return required to induce investment
generally equals the risk free rate of return plus a
risk premium whereas the expected rate of return depends on information and
information alone. The expected value of future flows sustains the expected
rate of return in a model of capitalized economic value described centuries ago,
never abandoned, made stronger ever since.
http://elementsoffinance.net/support/average_period_user_cost_and_term_structure.pdf
.
13. Learn that the shape of the intrinsic yield
curve depends on the degree of risk-sharing and risk-aversion between creditors
and shareholders.
http://elementsoffinance.net/support/neoclassical_term_structure.pdf
This
paper introduces diversification benefits from investment as a source of wealth
for the risk premium that sustains the growth of financial markets.
14. This study in The Financial Review [1986d], “The User
Cost and Capital Budgeting”, expounds on the
generalization of cash flow stream shapes from the perspective of the zero net
present value rule for determining the feasible investment set.
http://elementsoffinance.net/support/tfr_capital_budgeting.pdf
15. Learn that the demand price for real capital embodies
expected returns based upon economic information about discounted cash flows.
http://elementsoffinance.net/support/producer_theory_of_value_and_equilibrium_stock_returns.pdf
When
properly discounted expected cash flows provide an intrinsic value measurement
then market competition assures that required risk premia measurements from the
consumer theory of value vibrate randomly and unpredictably around the
information-based expected returns (Bachelier 1893, 1906 and Paul Samuelson
1965). Burton Malkiel (Princeton U) writes wrongly in A Random Walk Down
Wall Street (1968) that risk and risk alone determines the level of
equilibrium rates of return. Correction:
Risk and risk alone determine the required risk premium added to the risk-free
rate, a societal rate with concrete components independent of preferences. Risk
determines only the required rate of return and not its dual, the expected rate
of return. Information and information alone determines
expected rates of return. With well functioning
markets and wise public policy, competitive rates of returns vibrate randomly
around an idiosyncratic, asset specific intrinsic value.
16.
This study incorporates debt maturity structure into intrinsic value by
focusing on the zero net present value equilibrium condition in the market for
real assets. Market equilibria implies that the net
present value of the marginal investment is independent of the financing method
therefore user costs for alternative debt contracts equilibrate. The user cost
specification therefore implies a determinate relationship between interest
rates on alternative debt contracts.
http://elementsoffinance.net/support/embodied_equity_theory_of_term_structure.pdf
Analysis
of the user cost specification reveals that the equilibrium interest rate is an
increasing function of the debt contract's loan-to-value ratio and debt
duration (its elasticity , average period). The basic
reason why the interest rate increases with average period is this: the equity
financing rate exceeds the interest rate, a
lengthening debt average period reduces to equity the discounted cost of debt
and the financing rate increases to re-establish equilibrium. The “embodied equity”
hypothesis advanced herein joins the expectations hypothesis, the liquidity
preference hypothesis, and the market segmentation hypothesis as fundamental
explanations for the normal upward slope on the yield curve.
17. This study analyzes a specification for the
user cost of capital that reveals fundamental implications for interpretation
and measurement of marginal effective income tax rates.
http://elementsoffinance.net/support/marginal_effective_tax_rates.pdf
A
novel and surprising finding is that the marginal effective income tax rate is
invariant to asset characteristics such as service life and capacity
depreciation through equilibration by the user cost of capital that maintains a
zero net present value for marginal investments. Maybe the findings echo Paul Samuelson (1963)
regarding the invariance of asset intrinsic value to the marginal income tax
rate.
18. Another nonclassical study that endogenizes
debt maturity into the intrinsic value of a hypothetical balance sheet shows
different recognizable formulations therein for the financial cost of capital.
http://elementsoffinance.net/support/debt_maturity_and_cost_of_capital.pdf
19. The important issue of government tax shields
squeezing out private investment is significant.
http://elementsoffinance.net/support/tfr_tax_shields.pdf
20. In a nutshell, or rather with a lightbulb,
the tale describes how current productive capacity relative to intrinsic value
in nothing at all like a constant.
http://elementsoffinance.net/support/Current
Cost Accounting - Fallacy of the Lightbulbs - 1992.pdf
21. This 1986 study expands on the response of
intrinsic value to a change in the interest or discount rate. The relationship
is not unidirectional but rather is bidirectional and depends of a ratio of
marginal to total interest elasticity.
http://elementsoffinance.net/support/Duration
and discount rate changes-bcwp86-10.pdf
22. This 1984 study examines the relation between
capital investment and surplus.
http://elementsoffinance.net/support/Capital
Investment and Surplus-bcwp84-35.pdf
22. This study with co-author Prof George Aragon
at Boston College establishes the similarity of the equity Price-to-Book ratio
to the Market Cap over Current Cost ratio
http://elementsoffinance.net/support/QandPB
- Aragon Downs -1992.pdf
24. My doctoral dissertation from Purdue
University approved December 1982, “The Effects of Inflation and Taxation on
the Value of Capital” is item=8310819 at ProQuest. Therein the differential
effect of LIFO versus FIFO inventory accounting method on intrinsic value is
specified and accounted for though no later manuscripts utilize that particular
reality check! The Full Committee includes Prof Patric Hendershott (Head),
eventual Minister without Portfolio for the Republic of China (Taiwan) Prof Hu
Sheng Cheng, Prof Gary Schlarbaum, and Prof James Moore.
The
Effects of Inflation and Taxation on the Value of Capital
25. This paper, coauthored with then Ph.D.
student Cűneyt Demirgűreş, examines
country funds trading on the NYSE or AMEX comprised of common stocks trading on
foreign exchanges. We find high positive
correlation among premiums for country funds and conclude a "foreign-fund
investor sentiment" is systematic to all country funds. Premiums and domestic market indexes
correlate positively for funds investing in developed-economies (which largely
concentrate in the hands of individual investors) and negatively for funds
investing in developing-economies (which primarily are held by
institutions). Returns on country funds
and domestic indexes correlate positive irrespective of ownership
structure. These results suggest that
foreign and domestic investors use different information in setting asset
prices thus giving support to the investor sentiment hypothesis.
http://elementsoffinance.net/support/investor_sentiment_closed_end_country_funds.pdf
References and Additional Readings
[1989a] Cutler, David M.,
James M. Poterba, and Lawrence H. Summers. “What Moves Stock Prices?” Journal
of Portfolio Management, 1989, vol 15 (3), pp 4-12.
[1987a] Downs, Thomas W and Patric H.
Hendershott; “Tax Policy and
Stock Prices”;
National Tax Journal vol 40 (2), June 1987, pp 183-190.
[1986a] Downs, Thomas W;
Text of the presentation read by me that introduces the intrinsic value model
at the NBER Summer Research Institute, Cambridge MA; 2026.0731
[1986b] Downs, Thomas W
and Hendershott, Patric H; NBER Working Paper #2094 is the presentation paper
with few exceptions.
[1986c] Downs, Thomas W; “Using the User Cost”; Journal of Economics and Business vol 38, pp 297-305; Fall 1986.
[1986d] Downs, Thomas W, “The User
Cost and Capital Budgeting”; The Financial Review, vol 21 (2), May 1986, pp
277-287.
Downs,
T. and Tehranian, H., "The Differential Impacts of Tax Policy Changes on
Industry Stock Prices," Boston College SOM Working Paper 86-90 (October
1986).
bcwp86-10-19860115.pdf
bcwp84-35-19840915.pdf
[1981a]
Summers, L.H., "Taxation and Corporate Investment: A Q-Theory
Approach,"
Brookings
Papers on Economic Activity
(1981:1) , pp 67-127.
[1979a]
Summers, L.H. and Martin Feldstein; "Inflation and the Taxation of Capital
Income in the Corporate Sector," NBER Working Paper 312 (1979)
[1936a] Keynes, J. M. (1936). The
General Theory of Employment, Interest and Money. London: Macmillan (1936).
The free add-in below for Microsoft Excel can create a new
algorithmic document in MS Word
useful for nearly any topic or purpose.
Package personalized learning content into algorithmic setups
embodying random redraws of worksheet cells.
Cells might contain a number, word, or an alphanumeric
phrase/sentence/paragraph made from other cells! Endless options to uniquely redraw
algorithmic scenario setups give teachers and students alike lots of choices.
Click http://elementsoffinance.net/Algogen.xla to download the add-in for Excel.
Better yet, first peruse this documentation below
then download the add-in! http://elementsoffinance.net/AlgorithmicDocumentGenerator.pdf
Installation Instruction #3 in the above pdf describes how to activate
two Excel add-ins – the free Algogen add-in above and the Analysis Tool-Pak add-in from Microsoft. Completing that step (only) empowers Word
& Excel with Algogen wizards that help package
your content into algorithmic scenario setups, a potentially high return on
invested time that enhances teaching and learning effectiveness and
efficiency. Find examples, hints, and
more in the documentation. For example,
the first pages present an analysis of student learning outcomes with multiple
attempt algorithmic online quizzes, multiple attempt algorithmic paper exams
submitted in class and/or online. The
sample includes thousands of students with varied teachers and course formats
(traditional, hybrid & online registrants).
All students populated one common undergraduate core course learning
community. All were challenged by the
same set of algorithmic assessments.
All software
resources listed herein are authored by prof-td@elementsOfFinance.net
and are available “as-is” subject to terms in the End User License agreement (EULA).
No liability nor benefit accrues to prof-td or elementsOfFinance.net
LLC by your use of these resources.
No harm is intended, either.
Hopefully you find unbelievably huge reductions in exam preparation time – for me the 18 hours per exam dropped down to
2 hours, a savings that accrued 4 times a semester (more than a complete
workweek)! The Algogen
app that prof-td uses even analyzes scantron results, transfers course data,
and makes a Standings page showing all student scores, publicly viewable and
anonymous, from 1st rank to last.
Everyone knows the performance outcomes of everyone else,
anonymously. With a handful of clicks Algogen made the prof a complete 25-question exam
with 4 unique versions ready for duplication onto paper for classroom use. The procedure also transfers the 25 answers
for the 4 exam versions into the gradebook.xlsx ready for the eventual Algogen click that processes the scantron data, no
matter how large or small the class. One
semester more than 1,200 students populated one common core course learning
community with prof-td.
Not
every teacher wants to make easy tests
but
every teacher wants to easily make tests.
This
is the textbook rights of reversion for complete rights on the Pearson editions
entitled Lessons about the structure of Finance by Thomas W. Downs. Freely use its child entitled Elements of Finance.
No harm is intended. Please notify me if any items on the website require
correction, change, or removal.
http://elementsoffinance.net/support/PearsonRightsReversion-2003.pdf
Get the free Algogen app that allows you to select finance scenario
setups from documents in an algorithmic content collection and make countless
new versions for purposes like quizzes, exams, assignments, presentation examples,
or for making algorithmic online practice scenarios or assessments, at http://elementsOfFinance.net/Algogen.zip
Documentation
provides installation instructions and more: http://elementsoffinance.net/AlgorithmicDocumentGenerator.pdf .
Get the free
algorithmic content collection written for the elements Of Finance book at http://elementsoffinance.net/elements.zip